
Financial-services AI agents will not earn trust simply by sounding human or feeling personalized. A trusted experience has two layers. The first is product experience: a clear promise, consistent behavior, relevant personalization and understandable language. The second is control architecture: visible scope, permission boundaries, evidence, auditability, escalation and explicit approval before high-risk action.
Consumer branding can teach the first layer. Financial governance determines whether the second is credible.
What consumer brands teach about trust
Clear promise
Financial-agent translation: Define the agent's job and non-job.
User-visible design: One-sentence scope + examples.
Risk if missing: Overtrust / scope ambiguity.
Consistency
Financial-agent translation: Use the same rules across channels and workflows.
User-visible design: Stable terminology, policy and confirmation behavior.
Risk if missing: The user cannot predict when the agent will act.
Personalization
Financial-agent translation: Use relevant context to make information more useful.
User-visible design: Editable goals, preferences and account context.
Risk if missing: Persuasion or inferred suitability.
Participation / control
Financial-agent translation: Let the user shape the experience.
User-visible design: Corrections, preferences, permissions, reject/confirm.
Risk if missing: The user feels trapped or manipulated.
Recognition / provenance
Financial-agent translation: Make source and publisher visible.
User-visible design: Agent owner, data source and tool/account identity.
Risk if missing: Unknown authority or impersonation.
Experience continuity
Financial-agent translation: Preserve context through handoffs.
User-visible design: Agent → specialist → human handoff with summary.
Risk if missing: Repetition, errors and hidden state changes.
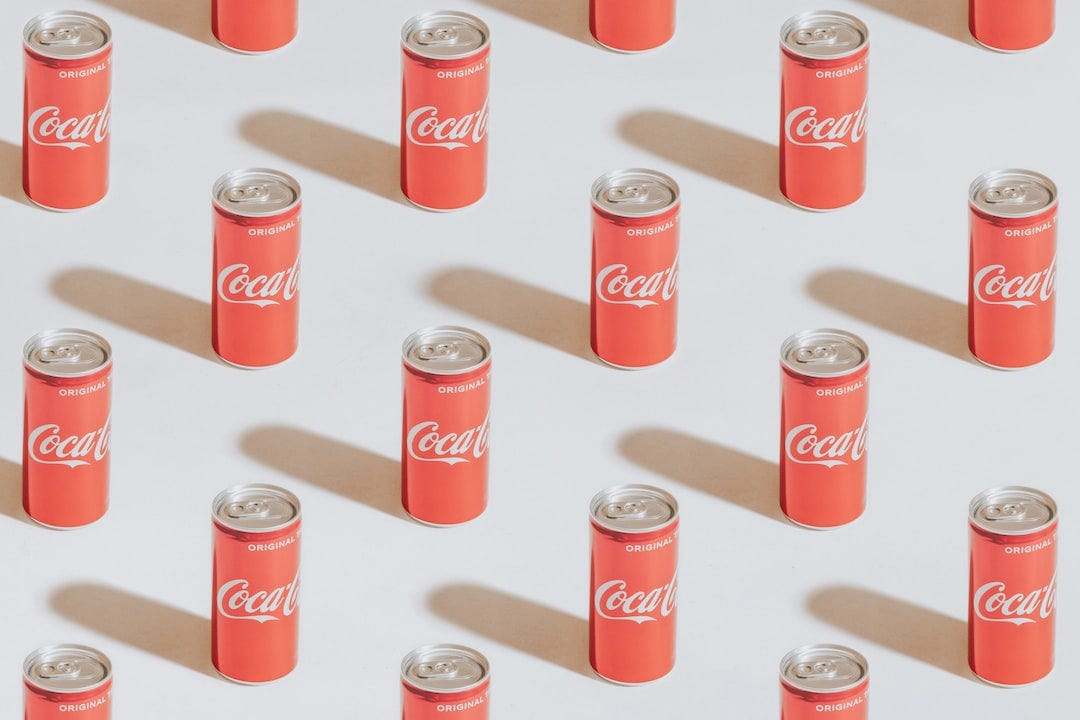
Strong consumer experiences make the promise easy to recognize. Coca-Cola's Share a Coke is a useful example: a familiar product was made more personal and participatory by replacing generic packaging with names and later connecting physical packaging to digital customization and sharing.
The lesson is not that personalization caused Coca-Cola's market value or competitive position. It is that a familiar promise can become more relevant when the user can see themselves in the experience and understand what the product is asking them to do.
Current Coca-Cola personalization flows also include boundaries such as preview and human review of custom submissions. That matters because personalization works best when users have control and the product preserves limits rather than accepting every input uncritically.
Where the branding analogy breaks in finance
A disappointing personalized bottle is a low-stakes experience. A financial agent can influence a transfer, investment decision, disclosure interpretation or account action with real economic consequences.
That changes the trust standard. Financial loss, conflicts, privacy, suitability or fiduciary questions, and irreversible actions cannot be solved by tone, familiarity or a good interface.
FINRA's 2026 guidance highlights autonomy, scope of authority, auditability and transparency as material concerns for agentic AI in financial settings. The FCA similarly emphasizes consumer trust and appropriate human oversight in wealth-management AI adoption.
The product therefore needs to earn trust twice: first through a clear experience, then through explicit authority controls.
Seven trust principles for financial AI agents
1. Clear promise
User question: What is this agent for?
Product requirement: Explicit job, scope and exclusions.
Metric: Scope comprehension.
2. Visible authority
User question: What can it read or do?
Product requirement: Expose read/write, tool and financial limits before connection.
Metric: Permission comprehension.
3. Evidence
User question: Why is it telling me this?
Product requirement: Show source, freshness, calculation/assumption and relevant disclosure.
Metric: Evidence-open / correction rate.
4. Predictability
User question: When will it ask before acting?
Product requirement: Consistent risk-based confirmation policy.
Metric: Unexpected-action incidents.
5. Reversibility
User question: Can I undo or stop it?
Product requirement: Cancel, revoke or escalate where technically possible; warn when irreversible.
Metric: Revoke/cancel success.
6. Escalation
User question: When does a human or user take over?
Product requirement: Handoff on ambiguity, failure, missing data or high-risk action.
Metric: Appropriate escalation rate.
7. Accountability
User question: Who owns the system and outcome?
Product requirement: Publisher/operator identity, audit trail and remediation path.
Metric: Resolution time / audit completeness.
Personalization should make the agent clearer—not more persuasive
Language / complexity
Good use: Explain a disclosure in plain or technical language.
Bad use: Hide material risk because a user prefers concise copy.
Control: Material facts always remain.
Priority / ordering
Good use: Surface the most relevant alert or document section.
Bad use: Rank by product commission or conversion without disclosure.
Control: Conflict policy + ranking rationale.
Goals / preferences
Good use: Use explicit goals to contextualize scenarios.
Bad use: Infer risk tolerance from clicks or wallet activity alone.
Control: Editable explicit profile.
Channel / cadence
Good use: Respect preferred notification timing.
Bad use: Use urgency or FOMO to increase trading or product uptake.
Control: Frequency controls / quiet settings.
Next action
Good use: Prepare a relevant workflow or checklist.
Bad use: Auto-execute because a similar action was accepted before.
Control: Fresh confirmation for consequential action.
A financial agent should use personalization to improve comprehension, sequencing and relevance. It should not use the same context to become more persuasive when the user is making a higher-risk decision.
Make permissions feel like part of the experience
Data access
User-facing requirement: Accounts/data categories and freshness.
Trust purpose: Prevents hidden context expansion.
Tool access
User-facing requirement: Which external system the agent can call.
Trust purpose: Defines the authority surface.
Read vs. write
User-facing requirement: Observation only vs. ability to change, send or transfer.
Trust purpose: Separates information from action.
Financial limit
User-facing requirement: Amount, product or transaction constraints where relevant.
Trust purpose: Bounds economic authority.
Duration
User-facing requirement: One-time, session or ongoing authorization.
Trust purpose: Prevents indefinite permission ambiguity.
Confirmation
User-facing requirement: When fresh approval is required.
Trust purpose: Makes high-stakes behavior predictable.
Revocation
User-facing requirement: How to disconnect or reduce permissions.
Trust purpose: Preserves user control.
Explain what the agent knows—and what it does not
What data or source was used and when it was last updated.
Which agent or tool produced the result.
The key assumption or rule driving the explanation or proposal.
What remains unknown, missing or uncertain.
Material fees, conflicts or limitations relevant to the output.
Whether the output is informational, a proposal, or an action awaiting approval.
The SEC's 2026 investment-management remarks are useful here because they describe AI agents as potential bridges between investors and complex disclosures. That is a strong use case precisely because the source material can remain visible. The agent can simplify the language without inventing a term that is not in the approved document.
Build human oversight into the user journey
Human oversight should not appear only after an agent fails. It should be designed into the workflow for ambiguity, repeated failure, missing material data, sensitive decisions and high-risk or irreversible actions.
A practical flow is: the agent handles a routine low-risk task → detects an escalation condition → pauses → summarizes what it knows, what failed and what decision remains → hands control to the user or a qualified human without losing context.
OpenAI's agent guidance similarly recommends human intervention for sensitive, irreversible or high-stakes actions. That is a general software design pattern, not a substitute for finance-specific regulatory or supervisory requirements.
Financial AI use cases that benefit from this design
Disclosure / document Q&A
Agent can help with: Explain fees, redemption, strategy and conflicts from approved documents.
Required boundary: Cite the source; do not invent missing terms.
Primary trust signal: Source / evidence.
Client-service triage
Agent can help with: Classify a request, gather context and route it to the correct team or workflow.
Required boundary: No unauthorized account changes.
Primary trust signal: Scope + handoff.
Portfolio / cash monitoring
Agent can help with: Surface changes against user-defined thresholds.
Required boundary: Alert does not equal recommendation; freshness is visible.
Primary trust signal: Data freshness.
Compliance / operations
Agent can help with: Summarize cases, reconcile inputs and prepare records.
Required boundary: Human review for material filings or decisions.
Primary trust signal: Audit trail.
Proposal preparation
Agent can help with: Draft an action with amount, cost and risk context.
Required boundary: Stop before high-risk execution unless exact authority is confirmed.
Primary trust signal: Confirmation.
Where Bluwhale fits
Bluwhale supports a financial-intelligence approach that brings connected data and AI-agent experiences closer to the people using them.
For financial-services teams, the starting point is a clear use case: which customer need the experience addresses, what information it uses and how people review the resulting recommendation or action.
Trust can be made inspectable: users and enterprise teams can see the agent's job, its evidence, its authority boundary and where control changes hands.
Trust is the experience plus the control system
Consumer brands show why familiarity, personalization and participation matter. Financial AI adds a harder requirement: the user must understand not only what the agent says, but what it is allowed to do.
That is the shift from brand experience to agent trust. A clear promise gets the user into the workflow. Visible evidence, bounded permissions, predictable confirmations, escalation and accountability are what make the workflow credible enough to continue.
Explore AI agents for financial services
Related reading
specialized financial agent fleet