
An AI personal finance assistant can help structure a weekly money review around four outputs: what changed, which records explain it, what is coming next and what you need to decide. Use the same account scope and a clear review date so that each session is comparable.
Think about the last time you checked your money. You may have opened a banking app, a brokerage account and a wallet, then tried to remember which payments were still coming. An AI personal finance assistant becomes more useful when the information and your goal are connected. This article applies that idea to a repeatable weekly routine, with illustrative calculations you can use to structure your own review.
AI personal finance assistant guide: start with one weekly question
“What changed in my money this week? Show me the transactions behind the biggest change, leave out transfers between my own accounts, and list any bills I told you are due before Friday.”
Give the assistant a cutoff date and the accounts you want included. If you know a bill is coming but it hasn’t posted, include its due date in your question. Save the answer so you can pick up any loose ends next week.
If you are still choosing the service, start with the AI financial assistant guide. This article focuses on the recurring review after that choice.
Prepare a consistent starting point
Choose a regular review day and note the cutoff time. Record which accounts are included, when their data last refreshed and whether any entries are still pending. If a connection is temporarily unavailable, label that account as missing rather than interpreting the combined total as a complete picture.
Gather upcoming bill dates and expected income separately from completed transactions. A future payment, an authorization still pending and a settled transaction describe different stages of an event. Keep those stages visible so they do not become duplicate expenses.
If your bank updated this morning but your exchange last synced on Thursday, write down both dates. A change in the combined balance is easier to explain when you know which figures are current.
What Bluwhale brings to the weekly conversation
With Bluwhale for Individuals, you can see your bank accounts and digital assets in one profile. Start with WhaleScore, then look at the accounts and holdings behind it. If the wallet makes up more of your portfolio than it did last Friday, check whether you added funds or the assets you already held changed in price.
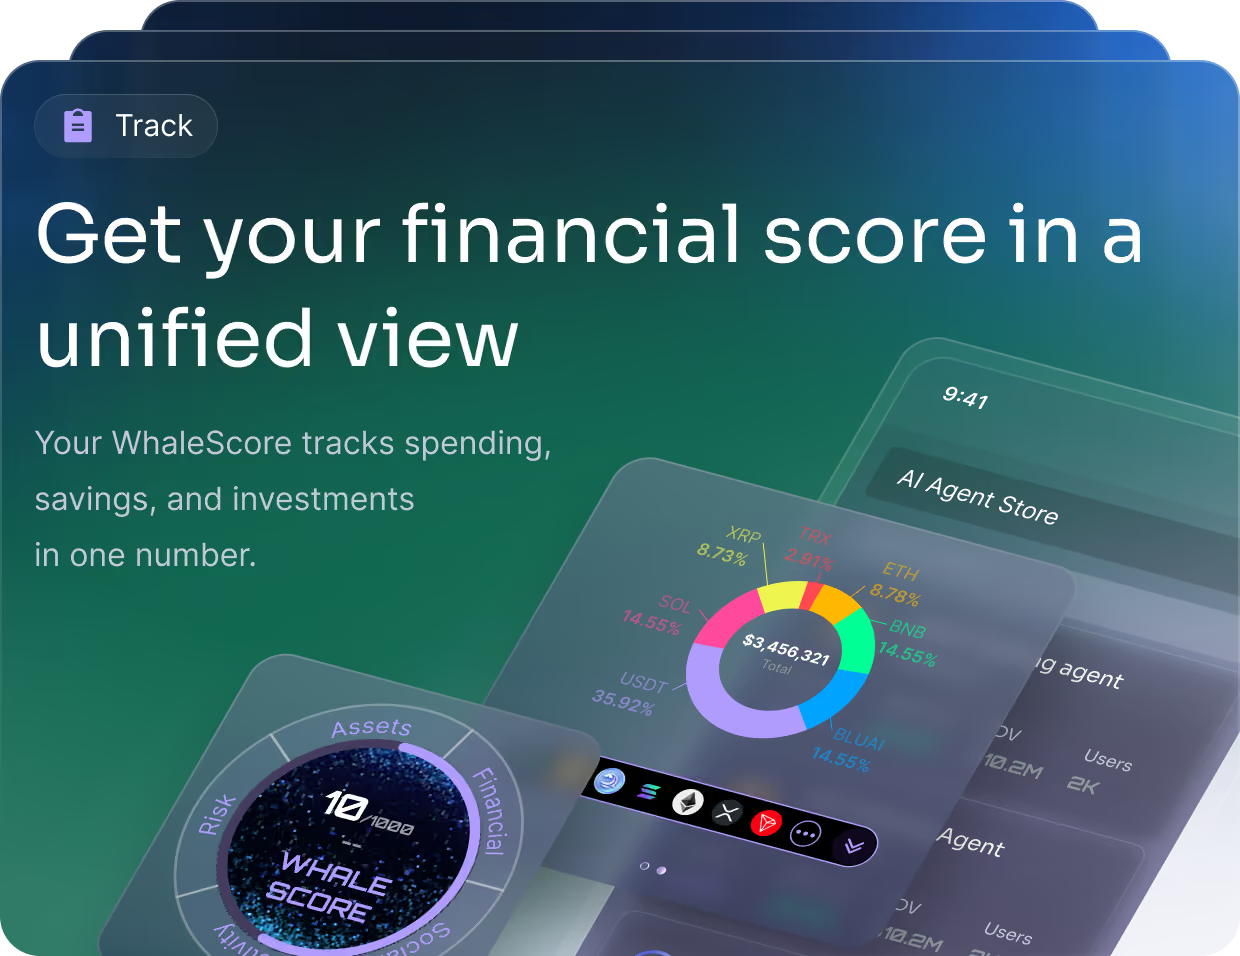
Now bring the review back to your next decision. If rent is due on Monday, check the available balance in the account that pays it. A higher portfolio value can lift your overall position while leaving that bank balance exactly where it was last week.
Explain what changed and why
Ask for a short list of significant changes, with the source records that support each explanation. Start with balances, incoming money, bills and transfers. Then examine unusual entries instead of reviewing every familiar transaction in equal detail.
For a fictional example, suppose cash rises from $1,400 to $1,750. The records show $900 of income and $550 of outflows. Those events explain the $350 increase. If the assistant instead attributes the increase to reduced spending, ask which comparison period supports that statement. A balance movement and a spending trend answer different questions.
Next, separate financial changes from data changes. A previously missing account can increase the displayed total without adding any new wealth. A corrected category can change a spending chart without changing the bank balance. Recording the cause prevents the following week's review from starting with the same confusion.
- Observed: a dated transaction or balance in the records.
- Calculated: a total derived from those records.
- Inferred: an explanation that needs confirmation or additional context.
For Bluwhale users, the connection between visibility and action is the important next step. A combined balance gives context, while your actual payment dates and commitments determine what can be put to work. Keep the reserve for a near-term obligation explicit when considering an agent strategy.
Look ahead to the next review
List commitments due before the next review and the dates of expected inflows. Ask the assistant to show the sequence, not just subtract monthly totals. Keep money reserved for a known obligation visible when reviewing what remains available.
For example, a fictional $700 bill due Tuesday and $900 payment expected Friday should appear as separate dated events. Whether Tuesday's bill is covered depends on available cash before Friday. The CFPB's money-management toolkit provides a bill calendar and cash-flow planning resources that can support this step.
Finish with specific questions: Does the expected reimbursement have a confirmed date? Has a subscription cancellation taken effect? Is a large purchase already included? The assistant can help organize those questions; the answers should come from the relevant records or provider.
A ten-minute weekly invoice check
Choose a weekly cutoff. First list bills due before the next review, then match posted payments to invoice IDs, and finally list the bills still open. A $75 invoice marked “issued” and a $75 debit are only a possible match until the payee, reference and dates agree.
A useful weekly note has three lines: invoice ID, payment evidence, next action. If a bill is disputed, leave it open with a review date. At the next session, carry forward the unresolved item instead of asking the assistant to infer that it was paid.
Keep a short review log
Use four fields for each follow-up: the question, its source, the next step and the date to check again. A useful entry might read: “Reimbursement not received; employer confirmation dated Thursday; check the deposit next Friday.” That is easier to act on than a broad reminder to improve cash flow.
Keep information gathering separate from actions that move money or change an account. Before approving an action, review the destination, amount, timing and any relevant charges in the actual service. The weekly log records your decision and makes later follow-up straightforward.
Read about what a financial health score measures and Bluwhale’s financial agents. Then explore Bluwhale with one question from this week’s review, such as which account paid for a recurring bill.
How much detail should the weekly review include?
Focus on meaningful changes, upcoming commitments and unresolved questions. Keep the underlying records available when a summary needs checking.
What if an account has not refreshed?
Note the last available timestamp and the missing period. Revisit affected totals after the account updates rather than treating old data as current.